What is a cash offer on a house?
A cash offer on a house is an offer to buy without a mortgage. The buyer pays the full purchase price from their own funds, so the sale has no financing contingency and no lender-ordered appraisal. The transaction still runs through escrow and still records with the county, but it closes faster and with fewer ways to stall.
That is the working definition, and the pros and cons of a cash offer on a house follow from it. If you want the longer version, including where the money comes from and how proof of funds works, our guide to what a cash offer on a home is covers it. This article is about the decision: whether cash is better, for whom, and when a financed offer beats it anyway.
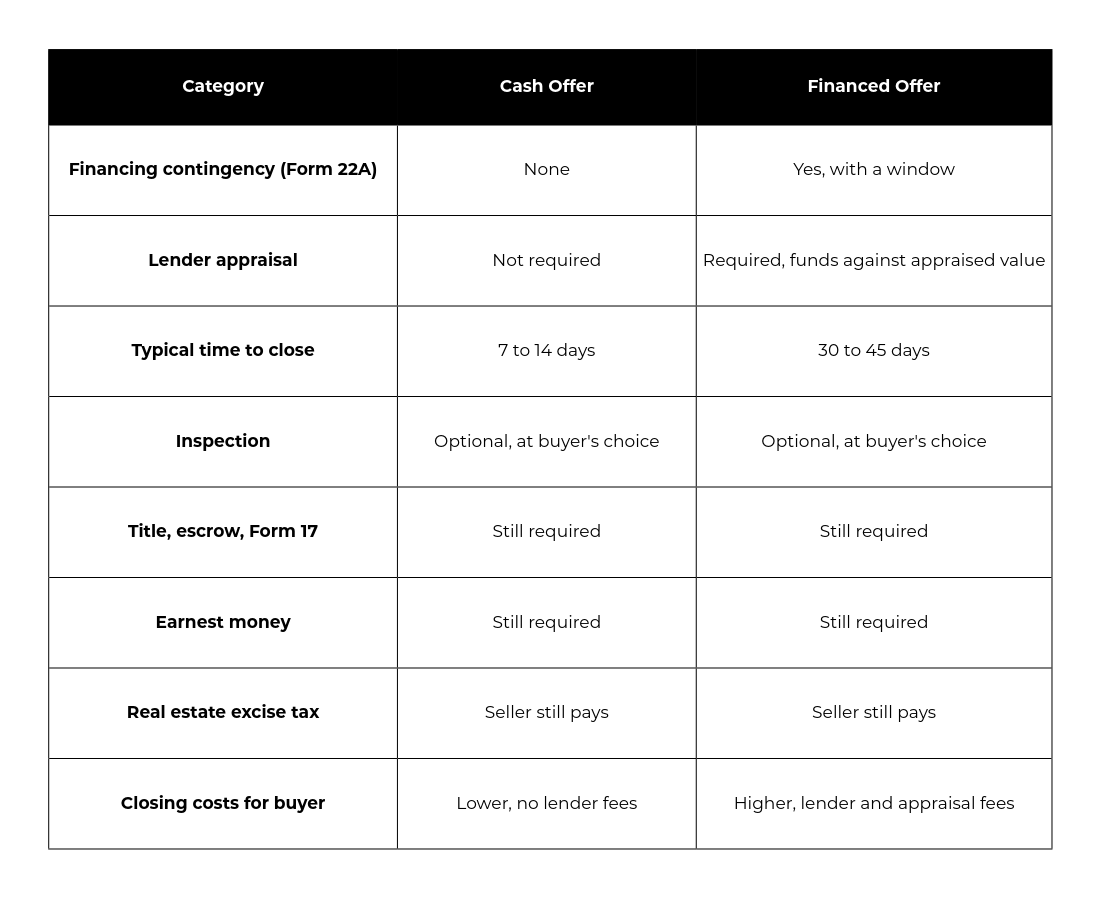
Cash offer vs mortgage: what actually changes?
Less than most people assume, and the differences are concentrated in one place.
What are the pros of a cash offer?
For a buyer, certainty and cost. For a seller, certainty and speed. The word certainty appears twice because it is the whole argument.
No financing contingency. The most common way a Washington deal stalls is a lender who has not finished underwriting by the contingency deadline. A cash offer has no such deadline.
No appraisal risk. A financed buyer who offers $60,000 over list can find their lender funding against an appraisal at list, and now they owe the gap in cash. A cash buyer already agreed to pay the number. The appraisal gap conversation never happens.
Faster close. Without underwriting, a cash sale can record in one to two weeks. In Washington, closing still happens at recording, but recording arrives sooner.
Lower closing costs. No origination fee, no lender's title policy, no appraisal fee. On a $900,000 purchase that is several thousand dollars the buyer does not spend.
No interest. The obvious one, and over 30 years the largest. A cash buyer pays the sticker price and nothing more.
Leverage. In a multiple-offer situation, a seller weighing a cash offer against a financed offer at the same price will take the cash almost every time. That leverage is real, and it is why cash offers often come in below asking and still win.
What are the cons of a cash offer?
The money is tied up, the discipline is optional, and the discount is not guaranteed.
Liquidity. Putting $900,000 into a house means $900,000 is not in an index fund, a business, or an emergency reserve. If the return on that money elsewhere exceeds your mortgage rate, paying cash costs you the difference every year.
Nobody is forcing you to inspect. A lender requires an appraisal partly to protect itself. With no lender, the only person protecting a cash buyer is the cash buyer. Skipping inspection because "there is no contingency anyway" is how cash buyers end up owning a foundation problem.
Sellers do not always discount. In a fast market with several offers, a seller may take the cash offer at full price or above. The convenience discount exists when the seller needs certainty more than they need the last dollar. It does not exist when three financed buyers are offering more.
Tax treatment is the same. A cash purchase does not change property tax, and Washington's real estate excise tax is paid by the seller regardless of how the buyer pays. There is no tax reason to prefer cash.
Delayed financing is possible but not automatic. Buyers who pay cash and later want to pull money back out can sometimes do a cash-out refinance within a set window, but the rules are lender-specific and the appraisal you skipped at purchase shows up here.
Are cash offers better for sellers?
Usually, and not always, and the difference is whether the seller needs certainty or needs the highest price.
A cash offer is better when the seller has already bought their next home and is carrying two mortgages, when the property has condition issues that would complicate a lender's appraisal, when the seller wants a fast recording date, or when a previous financed deal already failed and the seller is tired.
A financed offer is better when it is meaningfully higher and the buyer is fully underwritten with a short financing window. A $25,000 premium from an underwritten buyer with appraisal gap coverage is usually worth more than the certainty a cash buyer is selling.
The mistake sellers make is reading "cash" as a synonym for "strong." It is one form of strength. An underwritten financed buyer with a pre-inspection and a waived inspection contingency is nearly as certain and often pays more. Our checklist for competing with cash offers in Seattle shows what that offer looks like from the other side.
Do cash offers come in below asking?
Frequently, because the buyer is pricing the convenience they are providing.
A cash buyer knows their offer removes the seller's two biggest risks. They expect to be paid for that. In a slow market or on a property with issues, a cash offer 5% to 10% under a competing financed offer is normal, and sellers often take it. In a hot market with multiple financed offers over list, the cash discount shrinks or disappears, because the seller's certainty problem is already solved by volume.
One category that reliably comes in low: cash offers from companies that buy houses at scale. Those offers are built on a margin the company needs, and the convenience is real, but the price reflects it. If you are a seller who wants speed above all, selling your Seattle home for cash is a different path from listing, and it is worth understanding the tradeoff before you take an offer from anyone.
How do you compete with a cash offer?
By removing the same risks the cash buyer removed, using the tools a financed buyer actually has.
Get fully underwritten. Not pre-approved. Underwritten means a lender has reviewed your file and issued conditional approval subject only to the property. It is the closest a financed buyer gets to cash.
Shorten the financing window. A ten-day financing contingency instead of 21 tells the seller you expect to clear quickly.
Add appraisal gap coverage. NWMLS Form 22AD lets you commit to covering a shortfall up to a stated amount. It answers the seller's second-biggest fear about financed offers.
Pre-inspect and waive. A buyer who inspected before offering and waived the inspection contingency is nearly as certain as cash on the condition side.
Have your lender call the listing agent. A local lender who picks up the phone and vouches for your file does more for a seller's confidence than any letter.
Offer more. Certainty has a price. If the cash offer is $20,000 under yours and the seller is not in a hurry, your number wins.
What to know if you are buying with cash
Cash makes you a strong buyer. It does not make you a careful one, and the two are different.
Still inspect. You have no contingency forcing you to, which is exactly why you should. A sewer scope and a full inspection cost a few hundred dollars and are the only protection you have.
Still get title insurance. A lender would require a lender's policy. With no lender, buy an owner's policy for yourself. It is customary in Washington for the seller to pay for the owner's policy, so confirm it is in the contract.
Still budget for closing costs. Escrow, title, and recording fees apply. Lower than a financed close, not zero.
Decide whether cash is actually the best use of the money. If your mortgage rate would be below what the same funds earn elsewhere, financing and investing the difference can come out ahead over time. Run that comparison honestly before you wire.
Ask about delayed financing before you close. If you may want to pull cash back out later, know the lender's window and requirements now, while you can still order an appraisal cheaply.
What to know if you are selling and weighing a cash offer
Read the whole offer, not the word cash.
Verify the funds. A cash offer comes with proof of funds: a bank statement or letter showing the money is liquid and available. No proof, no offer. Fake cash offers exist, and our guide to cash offer scams covers how to spot one.
Compare on net, not on headline. A cash offer at $860,000 with a 10-day close and no contingencies versus a financed offer at $890,000 with underwritten approval and appraisal gap coverage. The second one nets you $30,000 more if it closes. Ask your agent what could still go wrong with each and price that risk.
Check who the buyer is. An individual paying cash and a company paying cash behave differently after mutual acceptance. Companies sometimes renegotiate after inspection as a matter of business model. Individuals usually do not.
Remember what does not change. You still complete Form 17. You still pay real estate excise tax. Closing still happens when the deed records. Cash shortens the timeline. It does not shorten your obligations.
Frequently asked questions
Do cash buyers still need an appraisal?
No lender requires one, so no. Cash buyers can order an appraisal on their own to confirm they are not overpaying, and many do on higher-priced or unusual properties. It is optional, not required.
How fast can a cash offer close in Washington?
Often 7 to 14 days from mutual acceptance, driven mostly by title work and escrow scheduling. Closing still happens when the county records the deed, so a Friday signing before a holiday weekend still means keys the following week.
Can you make a cash offer and then get a mortgage later?
Sometimes, through delayed financing, which is a cash-out refinance shortly after a cash purchase. Lender rules, timing windows, and appraisal requirements vary. Ask a lender before you close if this is your plan.
Is a cash offer always the winning offer?
No. A higher financed offer from a fully underwritten buyer with appraisal gap coverage frequently beats a lower cash offer, especially in a competitive market where the seller already has several strong options.
Deciding how to pay, or which offer to take
Cash is a tool, not a verdict. Buyers who have it should decide whether spending it is the best use of the money. Sellers offered it should compare the net, not the label.
At Every Door Real Estate, we help buyers structure financed offers that compete with cash, and we help sellers read a stack of offers for what each one will actually net after risk. If you are weighing cash against financing on either side of the table, talk with our team.
Check out this article next